What is equity compensation? Types, vesting & how to evaluate it
Published by SalaryGuide, with recruiter insight from our sister company, Search for Hire.
Equity compensation gives an employee a financial interest linked to the value of the company. It can be a meaningful part of an offer, particularly at startups and growth companies, but it should not be treated like guaranteed cash salary.
The value depends on the type of award, vesting schedule, company value, dilution, exercise requirements and whether there is eventually a way to sell the shares.
Common types of equity compensation
Restricted stock units
Restricted stock units, or RSUs, generally promise shares after specified vesting conditions are met. Employees do not normally need to pay an exercise price to receive vested RSUs, although the exact legal and tax treatment depends on the plan and jurisdiction.
Stock options
Options give you the right to buy shares at a specified exercise price, subject to the plan terms and vesting schedule.
The option can have economic value when the share value is above the exercise price, but private-company share values can change and liquidity may be limited.
Employee stock purchase plans
Some employers let eligible employees buy company shares through a structured purchase plan. Terms vary, so review the contribution rules, purchase schedule and any discount carefully.
Other long-term incentives
Companies can use other share, unit or value-linked awards. The label matters less than the actual rights, vesting conditions and payout mechanics in the documents.
What vesting means
Vesting determines when you earn the right to keep or exercise an award.
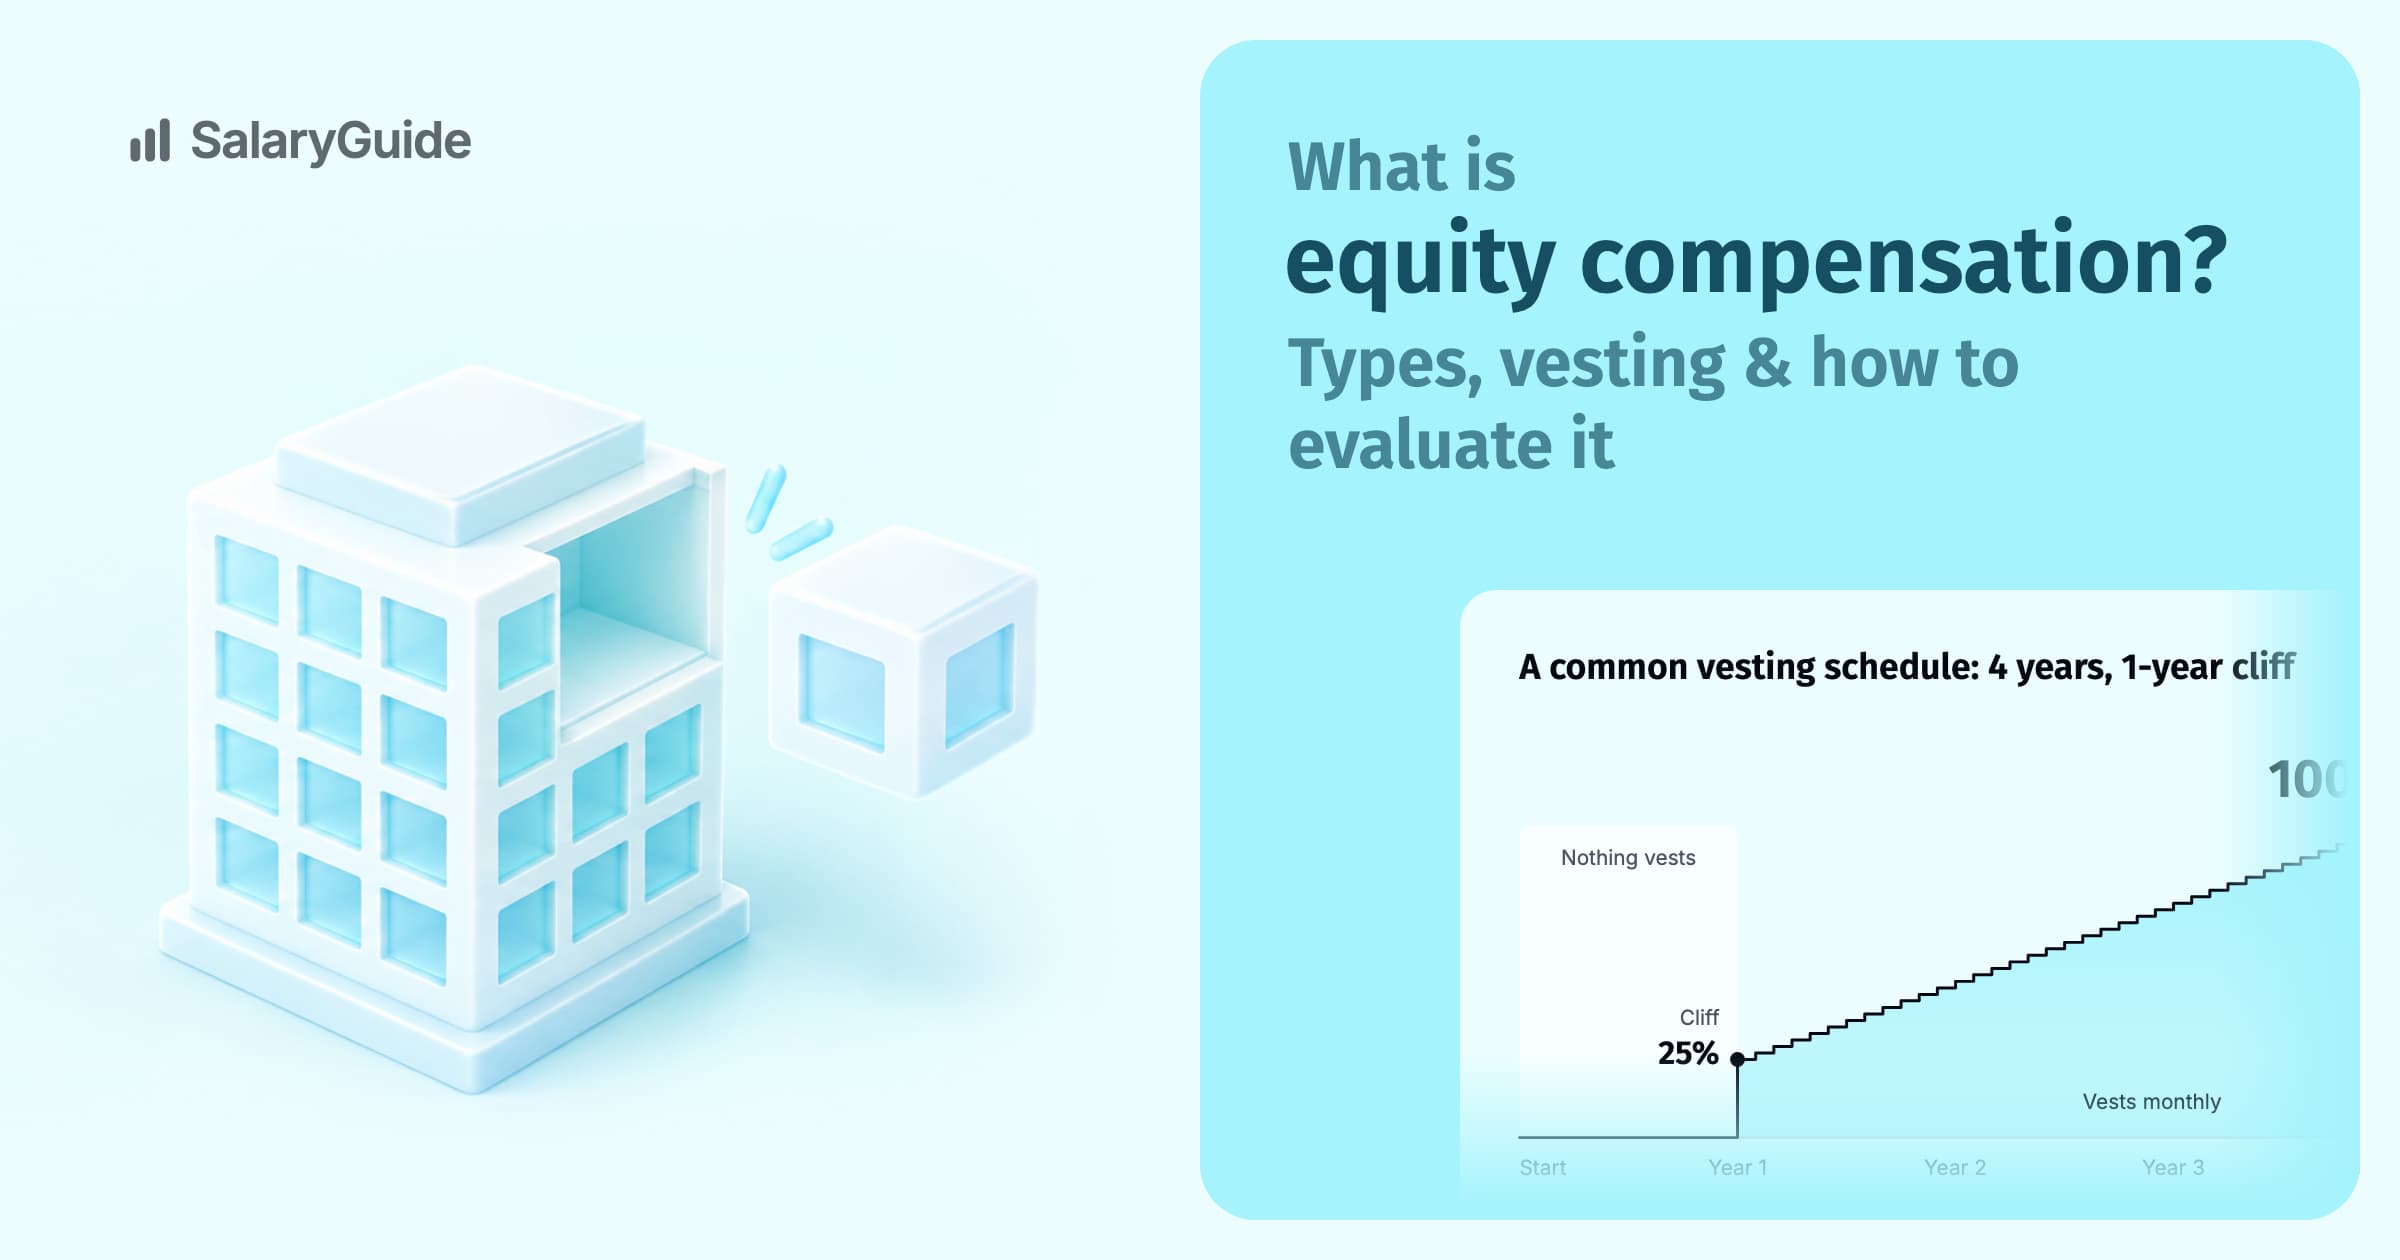
A common structure might spread vesting over several years, sometimes with an initial cliff before the first portion vests. Do not assume a particular schedule. Read the grant terms.
When comparing offers, ask:
- when vesting begins
- when the first portion vests
- how often vesting happens after that
- what happens if you leave
- whether vesting can accelerate in specific events
How to think about equity value
A quoted grant value can create false precision.
For a public company, market prices are visible, although they still move.
For a private company, employees may need more context. Useful questions include:
- What type of security am I receiving?
- How many shares or units does the grant represent?
- What is the relevant current valuation reference?
- What is the exercise price, if any?
- What percentage of the fully diluted company does the grant represent?
- Has the company raised capital recently?
- Is there any employee liquidity program?
Do not compare a private-company equity headline dollar-for-dollar with guaranteed salary unless you understand how that value was calculated.
Equity dilution
Dilution occurs when the company issues additional shares or securities, reducing the percentage ownership represented by an existing holding unless other adjustments apply.
That does not automatically mean the investment is worse. A company may raise capital to grow. But percentage ownership can change, so ask how the grant relates to the fully diluted share count rather than focusing only on the number of options or units.
How equity fits into total compensation
Keep the components separate when comparing offers.
| Compensation component | How to treat it |
|---|---|
| Base salary | Guaranteed cash compensation |
| Target cash bonus | Variable cash at target |
| Equity | Long-term, uncertain value |
| Benefits | Non-cash or indirect economic value |
Use the total compensation guide to compare the whole package without pretending each component has the same certainty.
How to evaluate an equity offer
1. Identify the award type
Options and RSUs have different mechanics. Start with what you are actually receiving.
2. Understand the vesting schedule
Know how long you need to stay before each portion becomes yours.
3. Understand the exercise requirement
For options, ask what exercising would cost and what happens after employment ends.
4. Ask about liquidity
For a private company, owning shares does not necessarily mean you can sell them when you want.
5. Consider concentration risk
Your salary and equity may both depend on the same company. More equity can create more upside, but also more exposure to one employer.
6. Understand tax uncertainty
Tax treatment can vary materially by award type, jurisdiction, timing and individual circumstances. Use the plan documents and qualified tax advice for decisions with significant tax consequences. This article is not tax advice.
Questions to ask the employer
- What type of equity is this?
- How many shares, units or options are included?
- What is the vesting schedule?
- Is there a cliff?
- What is the exercise price, if applicable?
- What share count should I use to understand percentage ownership?
- How was the quoted grant value calculated?
- What happens to unvested equity if I leave?
- What happens to vested options if I leave?
- Has the company offered employee liquidity in the past?
- Are refresh grants part of the compensation process?
How to negotiate equity
You may be able to negotiate:
- a larger grant
- a higher base salary if equity is uncertain
- a different cash/equity mix
- sign-on compensation to offset forfeited equity elsewhere
- clarity around refresh grants
- specific treatment in a change-of-control scenario where the employer offers it
Your leverage depends on the role, company stage and existing compensation framework. Compare the cash package with current market evidence using what is a competitive salary.
Equity and variable compensation are related but different
Equity can be used as an incentive, but it should not be treated as interchangeable with short-term cash variable compensation.
Cash bonuses are usually measured and paid over shorter periods. Equity often rewards longer-term value creation and retention, with more uncertainty around final value and liquidity.
The best way to judge an equity offer is to separate what is guaranteed, what is target cash and what is long-term uncertain value, then decide whether the overall mix fits your goals and risk tolerance.