Total compensation: what it includes & how to calculate it
Published by SalaryGuide, with recruiter insight from our sister company, Search for Hire.
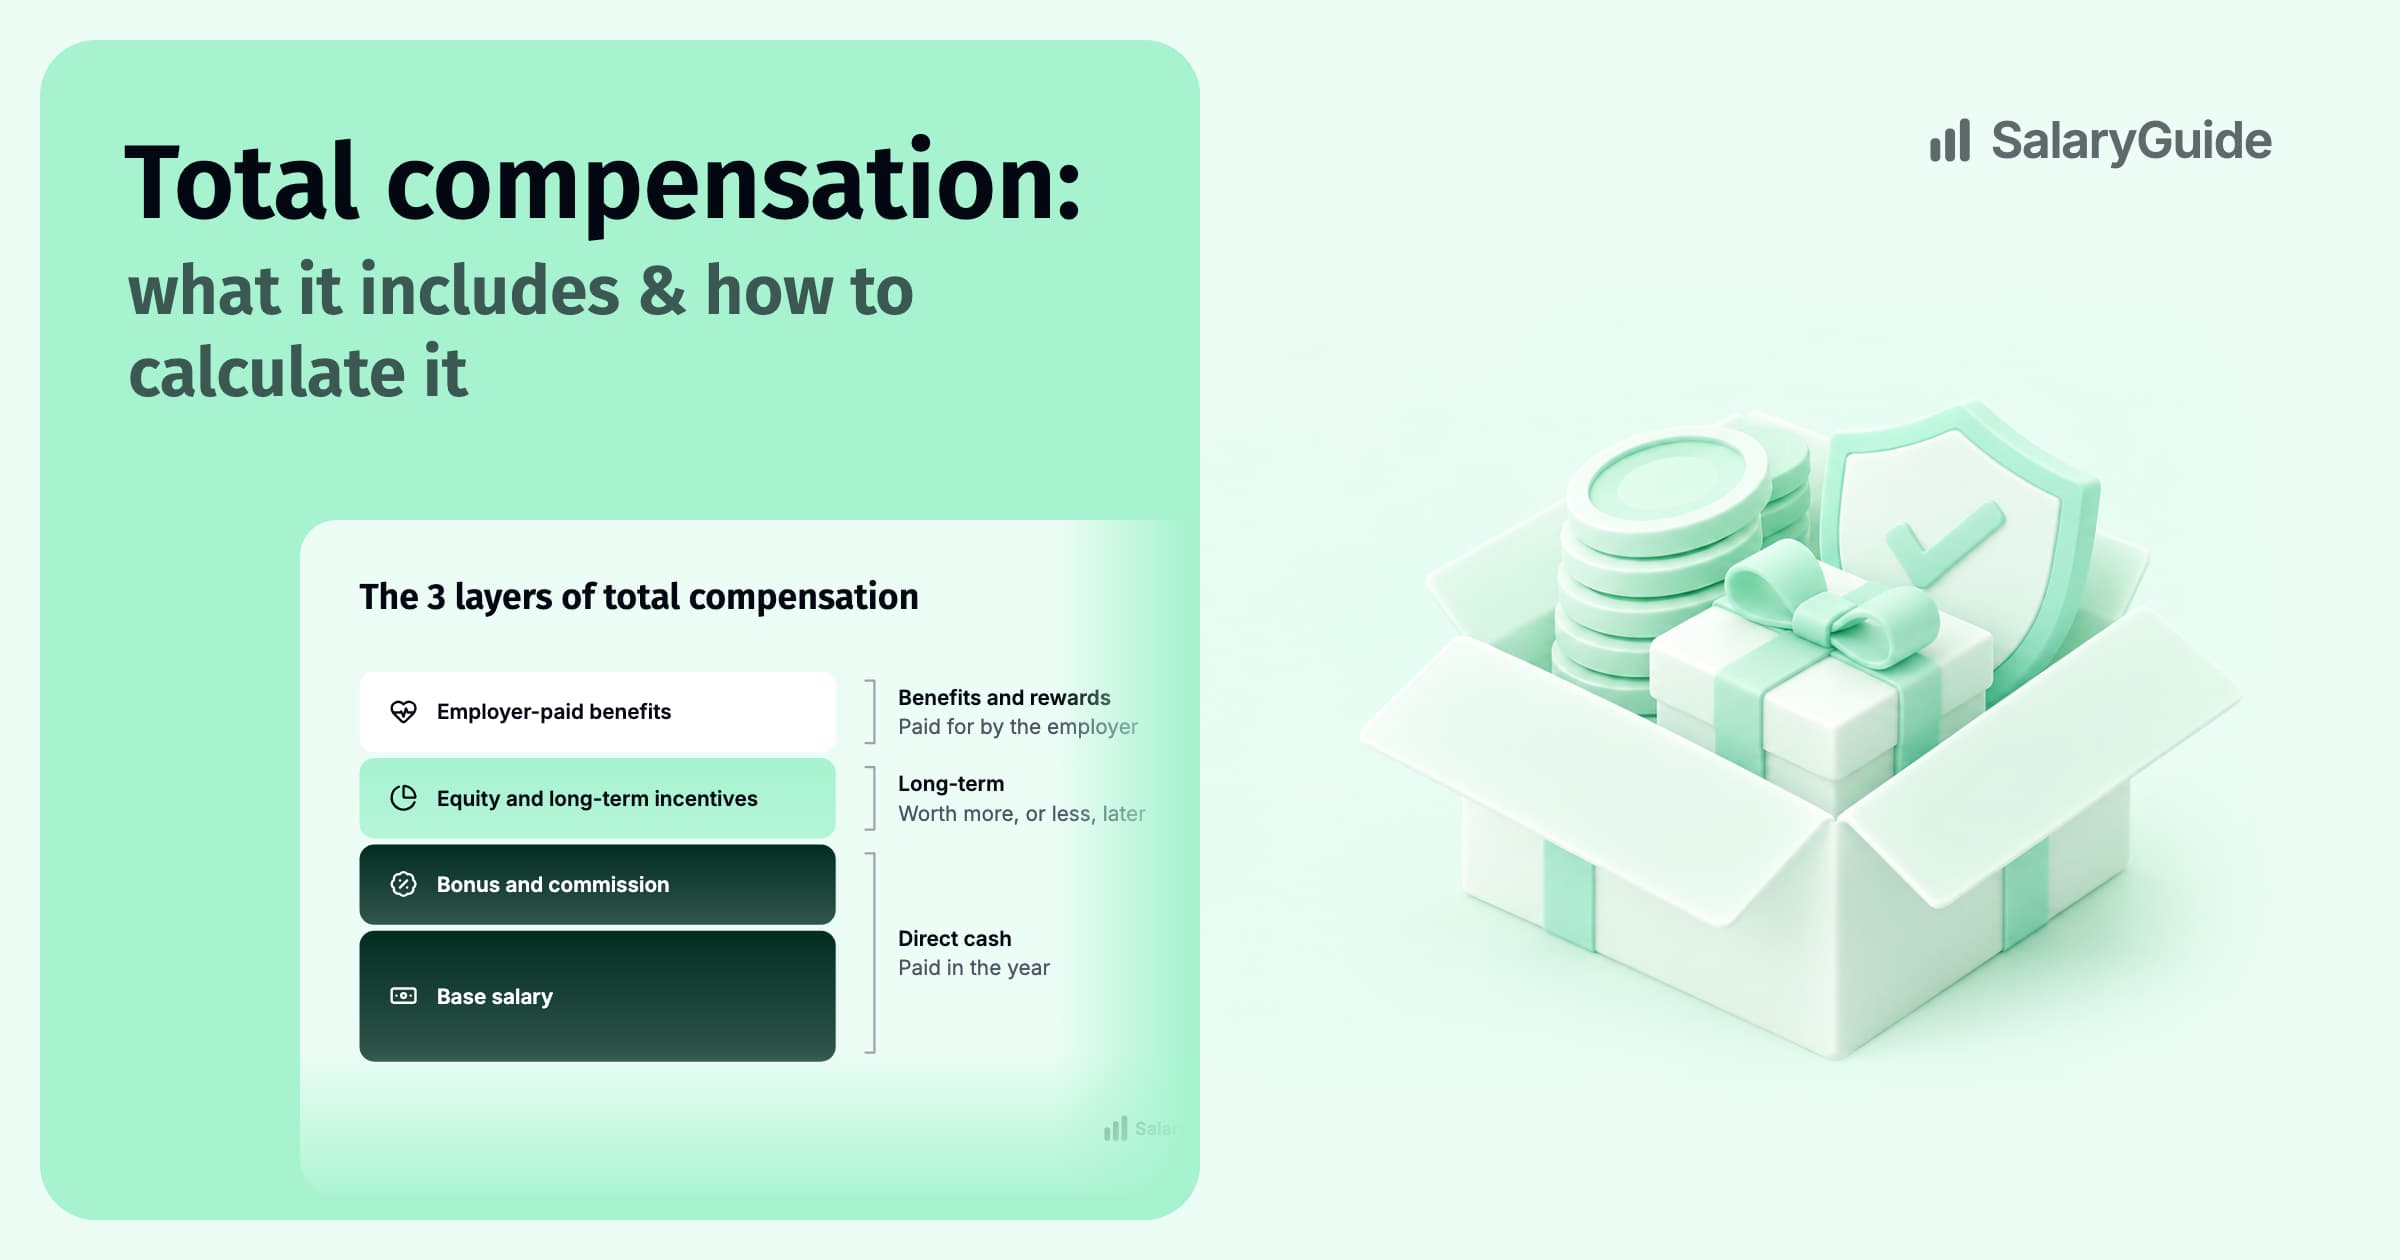
Total compensation is the combined value of the pay and employer-provided rewards attached to a job.
Base salary is usually the starting point, but two jobs with the same salary can have very different economic value once bonus, commission, equity, retirement contributions and benefits are included.
A useful total-compensation calculation makes those differences visible without pretending every perk has an exact cash value.
What counts as total compensation?
The answer depends on what you are trying to measure.
For comparing offers, it is useful to separate the package into three layers.
Direct cash compensation
- base salary;
- target or expected bonus;
- commission or other cash incentives;
- sign-on or guaranteed cash payments.
Long-term compensation
- restricted stock units;
- stock options;
- other long-term incentives.
Employer-paid benefits and rewards
- retirement contributions or match;
- employer health-insurance contribution;
- life or disability insurance;
- learning or professional-development budget;
- recurring allowances or stipends.
Some benefits are valuable but should not be treated as guaranteed cash. Keep the assumptions visible.
A simple total-compensation formula
For a one-year comparison:
Annual total compensation = base salary + expected cash incentives + annualized equity value + measurable employer-paid benefits
The word “expected” matters. A target bonus is not the same as a guaranteed bonus, and private-company equity is not the same as cash.
A one-year comparison model. Bonus and equity are expected values, not guaranteed cash.
Example: annual direct compensation
Imagine a marketing role with:
| Component | Annual value used for comparison |
|---|---|
| Base salary | $120,000 |
| Target bonus | $12,000 |
| Annualized RSU value | $15,000 |
| Employer retirement contribution | $4,800 |
| Employer health contribution | $7,200 |
| Professional-development allowance | $1,500 |
| Illustrative annual package | $160,500 |
This is a comparison model, not a promise that every component will turn into cash in the same year.
Step 1: record the guaranteed base salary
Use the contractual annual base salary. If the role is hourly, convert expected annual hours separately and note the assumption.
Do not mix base salary with bonus or commission when comparing against market salary data unless the data source explicitly measures total compensation.
Step 2: separate guaranteed and variable cash
For each bonus or commission component, record:
- target amount or target percentage;
- whether it is guaranteed, discretionary or formula-based;
- individual versus company performance conditions;
- payout frequency;
- recent payout history if the employer shares it.
For job-offer comparisons, you may want two numbers:
Guaranteed cash and target cash.
That makes the risk difference visible.
Step 3: annualize equity carefully
For public-company RSUs, a simple comparison can divide the grant value by the vesting period, while clearly noting that share prices can move.
For private-company options, avoid pretending the headline grant has a reliable cash value. You need the number of options, strike price, vesting terms and information about the underlying company value to make even a rough assessment.
If the information is incomplete, show equity separately rather than forcing it into the total.
Step 4: add employer contributions you can verify
Retirement match and employer-paid insurance contributions can materially change the package.
Use the amount the employer actually contributes, not the theoretical retail cost of buying a similar benefit yourself.
Step 5: treat paid time off and flexibility differently
For a salaried employee, paid time off is normally already funded through the annual salary. Adding “salary per day x vacation days” to the total can double count the same pay.
That does not mean PTO has no value. It means it is better treated as a package-quality factor unless you are using a specific employer-cost methodology.
The same is true for remote work and flexibility. They can have substantial personal value without being cash compensation.
Compare offers using the same rules
A useful worksheet uses identical categories for every offer.
| Component | Offer A | Offer B |
|---|---|---|
| Base salary | $125,000 | $115,000 |
| Target cash incentive | $5,000 | $15,000 |
| Annualized equity used for comparison | $0 | $12,000 |
| Employer retirement contribution | $3,750 | $5,750 |
| Employer health contribution | $4,800 | $7,500 |
| Recurring allowances | $1,200 | $2,000 |
| Illustrative measured total | $139,750 | $157,250 |
Offer B has the lower base salary but the higher measured package. Your decision may still favor Offer A if the bonus is uncertain, the equity is risky or the work itself is better suited to your goals.
Do not confuse employer cost with employee value
Employers may calculate total rewards using the full cost of benefits. Employees usually care more about the value they actually receive.
Those are different calculations.
For negotiation and offer comparison, focus on the components that affect your financial outcome and label uncertain amounts clearly.
Check the package against the market
Once you have separated base salary and total compensation, compare each against relevant market evidence.
Use SalaryGuide salary data and other credible sources for properly matched roles. If you are unsure how to judge the base offer, start with what is a competitive salary.
A high total package does not automatically make a weak base salary competitive if most of the difference depends on uncertain incentives.
Use total compensation in negotiation
A package view gives you more than one lever.
If base salary is fixed, possible alternatives may include:
- a sign-on payment;
- a higher target bonus;
- additional equity;
- a guaranteed first-year bonus;
- increased retirement contribution;
- professional-development budget;
- an earlier compensation review.
Use the salary negotiation guide for the broader conversation.
Total-compensation checklist
Before comparing offers, record:
- guaranteed base salary;
- guaranteed cash payments;
- target variable pay and its conditions;
- equity type, vesting and valuation assumptions;
- retirement contribution;
- employer health contribution;
- recurring allowances;
- important non-cash terms such as PTO and flexibility;
- one-year and, where useful, multi-year value;
- which figures are guaranteed, target, estimated or unknown.
The best total-compensation calculation is not the one with the biggest number. It is the one that makes the assumptions clear enough for two offers to be compared honestly.